
INTRODUCTION
The days of blindly submitting your income tax return and hoping for the best are completely obsolete. Today, the tax department leverages advanced artificial intelligence and powerful data analytics to relentlessly track every single financial move you make. If your declared numbers do not perfectly match their digital records, you risk triggering an instantaneous tax notice or a severely delayed refund. Current filling guidance highlights reconciliation with the Annual Information Statement (The Economic Times), confirming that accuracy and data matching are no longer optional.
The Annual Information Statement (AIS) is a massive, highly comprehensive document that consolidates all your financial transactions across the fiscal year. It pulls data directly from banks, employers, mutual funds, and stockbrokers to track everything from your basic salary to high-value property purchases. Leveraging this powerful tool before finalizing your tax filling is the ultimate strategy to catch dangerous errors, prevent crippling penalties, and ensure absolute compliance.
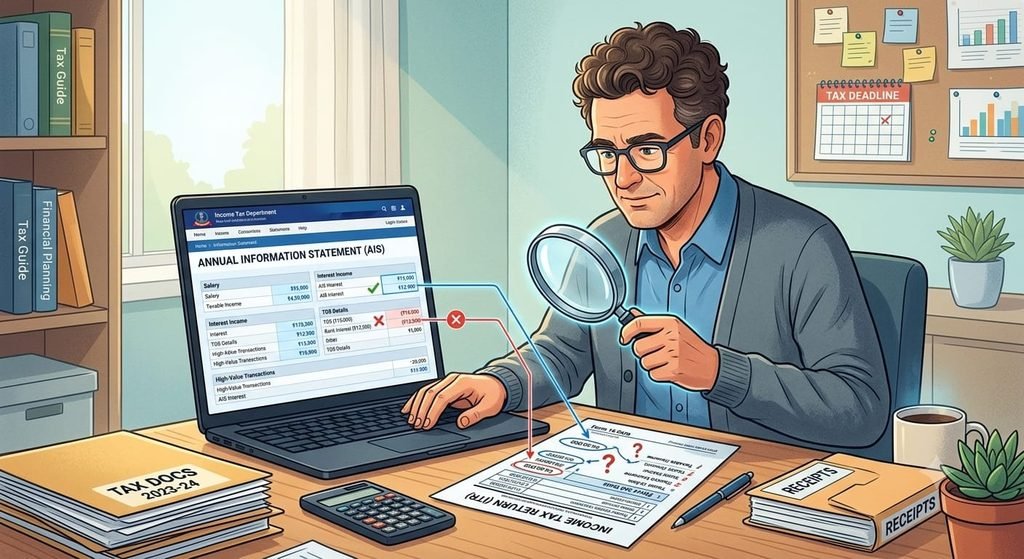
THE ARCHITECTURE OF THE AIS : WHAT THE GOVERNMENT ACTUALLY KNOWS
To utilize the AIS effectively, taxpayers must first understand its structural depth. It is not just a simple summary; it is divided into highly specific operational zones designed to give regulatory authorities a 360-degree view of your wealth.
Part A (General Information): This foundational section contains your core identity metrics, including your PAN, masked Aadhaar number, date of birth, and contact details.
Part B (Financial Data): This is where the real financial data lives. It aggressively tracks TDS (Tax Deducted at Source), TCS (Tax Collected at Source), specified financial transactions (SFT) like massive cash deposits or stock market movements, and demands or refunds from previous years.
AIS VS. TIS VS. FORM 26AS : NAVIGATING THE DATA GRID
A major point of failure in modern tax filling is confusing the various compliance documents provided by the government. Understanding the strict hierarchy of these digital records is critical.
Form 26AS: This remains the official, finalized record for your actual tax credits. When claiming TDS in your return, it must match Form 26AS precisely; when records conflict, Form 26AS always takes precedence for the purpose of your final return.
Annual Information Statement (AIS): This is the supreme data aggregation tool. It contains everything Form 26AS has, plus a massive array of non-taxed financial movements, such as savings account interest and mutual fund redemptions.
Taxpayer Information Summary (TIS): This is a simplified, category-wise aggregation of your AIS data. When you successfully submit feedback to correct an error in your AIS, the TIS automatically updates to reflect the new, derived value.
7 WAYS THE AIS ELIMINATES DEVASTATING TAX FILLING ERROR
1. EXPOSING HIDDEN AND FORGOTTEN INCOME STREAMS
Many taxpayers mistakenly report only their primary salary and completely forget secondary income streams. The AIS relentlessly captures background details like savings account interest, dividends, and short-term capital gains. By aggressively reviewing this data, you can spot and declare these hidden figures, effectively neutralizing the risk of under-reporting and severe tax evasion penalties.
2. NEUTRALIZING DUPLICATE TRANSACTION ERRORS
Reporting entities often make critical administrative mistakes, resulting in a single financial transaction appearing more than once in your records. For instance, a bank branch and its head office might accidentally both report the exact same entry. Checking your AIS empowers you to instantly identify these duplicates and submit an online feedback request to correct the system before it artificially inflates your tax liability.
3. RECTIFYING INCORRECT PAN ASSOCIATES
Financial data can occasionally get tangled by the reporting entity, resulting in transactions belonging to someone else entirely showing up on your personal statement. The AIS portal allows you to aggressively combat this by selecting a specialized feedback option stating that the information relates to another PAN or a different financial year.
4. RECONCILING MISMATCHED TAX DEDUCTIONS
Your tax credits must perfectly align with official government records to avoid catastrophic delays in your refund processing. Cross-checking these documents allows you to spot missing TDS credits, enabling you to force your employer or deductor to file a revised TDS return before you finalize your tax filling.
5. VALIDATING EXEMPT AND NON-TAXABLE INCOME
Even if a specific income stream is entirely exempt from taxes, the regulatory authorities still demand that it be fully disclosed on your return. The AIS rigorously tracks these non-taxable movements. If a transaction is exempt, you can use the built-in feedback tool to officially mark the information as “not taxable,” ensuring the department’s AI does not mistakenly categorize it as taxable revenue.
6. CORRECTING MISREPORTED CAPITAL GAINS
The taxpayer is explicitly required to compute and report the correct capital gains in the return, and errors involving indexation or exemption claims can result in tax demands running into the lakhs. Occasionally, a reporting entity might incorrectly report the gross redemption of a mutual fund instead of your actual capital gain.
7. TRACKING OVERSEAS ASSETS AND ESOPs
Omissions regarding foreign assets, overseas bank accounts, or ESOPs can trigger massive penalties under the Black Money Act, effectively pushing the combined tax and penalty burden to 120% of the undisclosed income. Taxpayers must act early to check their AIS for foreign asset data received under the Automatic Exchange of Information, ensuring these critical details are properly disclosed in Schedule FA (foreign assets) of their return.
THE 4-STEP BLUEPRINT TO CORRECTING AIS ERRORS
Step 1: Identify and Isolate: Log in to the government’s e-filing portal, navigate to the Services tab, and select your AIS. Locate the specific incorrect entry.
Step 2: Deploy Targeted Feedback: Click “Add Feedback” next to the entry and select the exact nature of the error. Options include “Information is not fully correct,” “Information is duplicate,” “Information relates to other PAN/year,” or “Information is denied”.
Step 3: Track the Entity Response: Once submitted, the reporting entity generally has 30 to 90 days to accept or reject your feedback. If accepted, your TIS and AIS will automatically update to reflect the corrected data with no further action needed on the portal.
Step 4: Download the Consolidated File: After submitting, you can download the AIS Consolidated Feedback file (ACF), which gives you a comprehensive PDF view of all your submitted feedback for easy tracking and understanding.
CONCLUSION
Mastering the Annual Information Statement is no longer a luxury but a critical necessity for the modern taxpayer. By treating the AIS as a proactive compliance tool rather than a static document, you can systematically eliminate reporting discrepancies before they escalate into legal challenges. Diligent monitoring, coupled with the strategic use of the government’s feedback mechanism, ensures that your tax filing remains accurate, transparent, and bulletproof.
REFERENCES
[1.] “How to Fix AIS/TIS Mismatches Before Filing ITR for AY 2026-27’’,Taxwapsi.[Online].Available:How to Fix AIS/TIS Mismatches Before Filing ITR for AY 2026-27 | Taxwapsi
[2.] ‘’AIS reconciliation before filling ITR AY 2026-2027’’, kcshah.[Online].Available:AY2026-2027’’,kcshah.[Online].Available:AIS Reconciliation Before Filing ITR AY 2026-27 | KC Shah
[3.] ‘’How to correct mismatches in AIS before filing your ITR for FY26’’,moneycontrol.[Online].Available:How to correct mismatches in AIS before filing your ITR for FY26
[4.] AI image references from Gemini.