Source: chatgpt
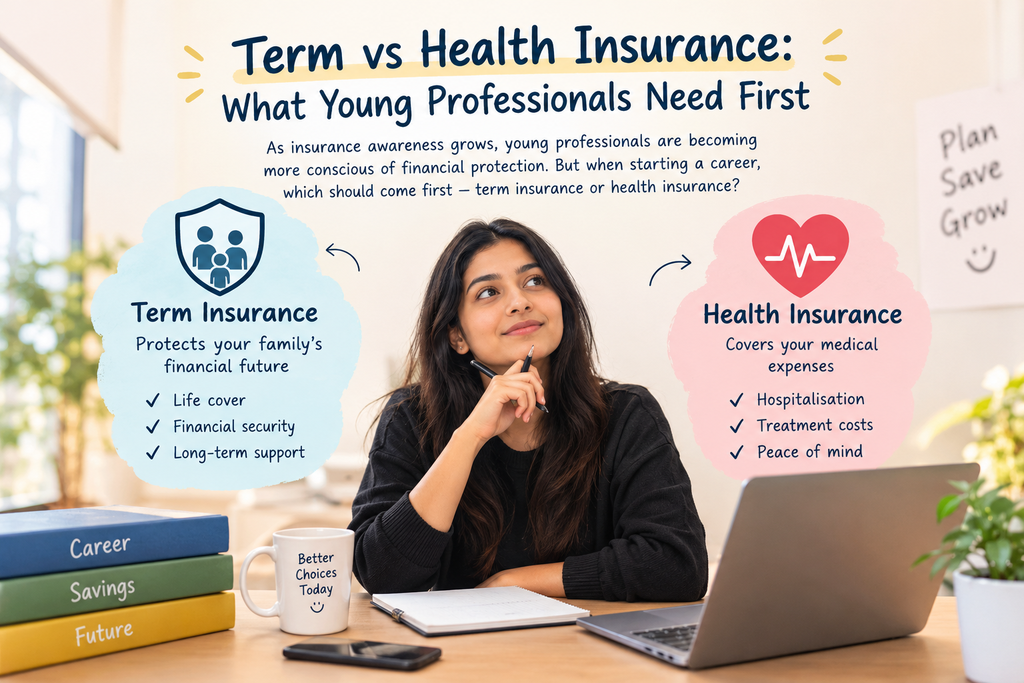
Term vs health insurance is an important comparison for young professionals starting their careers. Both types of insurance provide financial protection, but they cover different risks. Understanding their benefits can help you decide which coverage to prioritise based on your income, savings, and family responsibilities.
Health insurance helps cover eligible medical expenses according to policy terms, while term insurance provides financial protection for beneficiaries if the insured person dies during the policy term, subject to the policy conditions. The right choice depends on your personal circumstances and existing coverage.
Table of Contents
Term vs Health Insurance: Understanding the Difference
Term insurance and health insurance serve different purposes. Although both provide financial protection, they cover different types of risks.
Term insurance is a type of life insurance that provides financial support to the policyholder’s beneficiaries if the insured person dies during the policy period, subject to the policy conditions. It can be particularly useful for people whose families depend on their income.For example, a young professional who contributes to household expenses or pays a family’s loan instalments may want term insurance to help protect their dependants financially.

Source: When Does Term Insurance Become Important? – Search
Health insurance, on the other hand, helps cover eligible medical expenses according to the policy terms. Hospitalisation, certain treatments and other specified healthcare costs may be covered, depending on the plan.For someone who is just beginning their career, an unexpected medical bill can put pressure on savings. Health insurance can help manage this risk.

Source:https://static.vecteezy.com/system/resources/previews/029/936/125/large_2x/health-insurance-illustration-with-medical-document-form-for-healthcare-protection-service-in-flat-cartoon-hand-drawn-background-templates-vector.jpg
Why Health Insurance Can Be a Good Starting Point
Young people sometimes assume that health insurance is unnecessary because they are generally healthy. However, medical emergencies can occur at any age, and treatment costs can be difficult to manage without adequate financial protection.Having health insurance can help reduce the burden of eligible medical expenses and protect savings from being used entirely for healthcare.Employer-provided insurance is also helpful, but young professionals should check its coverage limits, exclusions and other conditions. They should understand what happens to their coverage if they change jobs or leave the company.If existing coverage is insufficient, buying an individual health insurance policy may be worth considering.
Understanding term vs health insurance helps young professionals decide how to protect their savings and manage financial risks.
When Does Term Insurance Become Important?
Term insurance becomes especially important when other people depend on your income.For example, a person supporting their parents, spouse or children may need to consider what would happen to the family’s finances if their income suddenly disappeared. The same applies to someone with a home loan or other significant financial commitments. Suitable term insurance can provide a financial cushion to beneficiaries and help them manage future expenses.However, a young professional who is financially independent, has no dependants and has limited financial obligations may not need substantial life insurance immediately.
The important point is to choose coverage based on actual responsibilities rather than buying a policy simply because others recommend it.
Insurance Awareness Is Becoming Part of Financial Planning
As more young people enter the workforce and begin managing their own money, understanding insurance is an important part of financial education.Insurance should not be viewed only as an additional monthly expense. It is a way to prepare for financial risks that could otherwise affect savings and family stability. At the same time, buying insurance without understanding the policy can create problems. A low premium does not automatically mean a policy offers the right protection. Young professionals should compare benefits, exclusions, waiting periods, coverage limits and claim conditions before making a decision. They should also be careful about confusing insurance with investment products, as these serve different purposes.
What Should Young Professionals Check Before Buying?
Before choosing health insurance, it is useful to compare the sum insured, hospital network, waiting periods, exclusions and out-of-pocket expenses. For term insurance, the amount of cover should be based on factors such as family expenses, outstanding loans, dependants’ future needs and existing savings. It is also important to read policy documents carefully and provide accurate information when applying. Rather than choosing the cheapest available option, young earners should look for coverage that fits their needs and remains affordable over time.
Which One Should Come First?
For many young professionals who do not have adequate medical coverage, health insurance is a sensible place to start. Term insurance deserves greater priority when parents, a spouse, children or other dependants rely on their income. People with both medical risks and family financial responsibilities may need both policies. There is no single answer that works for everyone. The right decision depends on personal circumstances, existing coverage and financial commitments.
When comparing term vs health insurance, consider your medical coverage, family dependants, income, and existing financial commitments.
Conclusion
Starting a career is a good time to build healthy financial habits, and insurance can be an important part of that process. Health insurance helps protect against eligible medical expenses, while term insurance helps protect dependants against the financial impact of the insured person’s death. Young professionals do not need to buy every insurance product at once. They need to understand their risks, compare their options and choose suitable coverage.
The goal is not simply to buy insurance early, but to buy the right protection before it becomes urgently necessary.
References
[1] Insurance Regulatory and Development Authority of India (IRDAI), “What is Health Insurance?” [Online]. Available: https://irdai.gov.in/health-dept. [Accessed: Oct. 16, 2026].
2] Life Insurance Corporation of India (LIC), “LIC’s New Tech-Term Insurance Plan.” [Online]. Available: https://www.licindia.in/tech-term
[3] Insurance Regulatory and Development Authority of India (IRDAI), “Policyholders’ Protection and Grievance Redressal.” [Online]. Available: https://irdai.gov.in/about-consumer-affairs
[4] Insurance Regulatory and Development Authority of India (IRDAI), “Health Insurers.” [Online]. Available: https://irdai.gov.in/insurers/health-insurers. [Accessed: Oct. 16, 2026].
Plagiarism Report:

Grammar Report:

AI Report: