Tech Tax Strategy For technology executives, corporate finance is no longer just about balancing ledger books or managing quarterly runway. It has evolved into a strategic discipline where code, capital allocation, and tax policy intersect. As tech companies scale—from high-growth SaaS platforms to global enterprise infrastructure providers—tax strategy directly affects cash flow, corporate valuation, and long-term competitive advantage.
Entering 2026, the corporate tax ecosystem presents both significant cash flow opportunities and regulatory hurdles. Tech enterprises face a landscape shaped by dynamic legislative changes, global minimum tax mandates, and evolving digital service frameworks.
Here is a strategic breakdown of how mid-sized and large technology enterprises can navigate the current fiscal climate.
1. Tech Tax Strategy Unpacking R&E Expenses: Domestic Relief vs. Offshore Realities
For years, technology firms navigated the heavy financial headwinds of mandatory capitalized research and development expenditures under Section 174. The requirement to amortize domestic software development over five years placed severe cash constraints on high-growth software engineering teams.
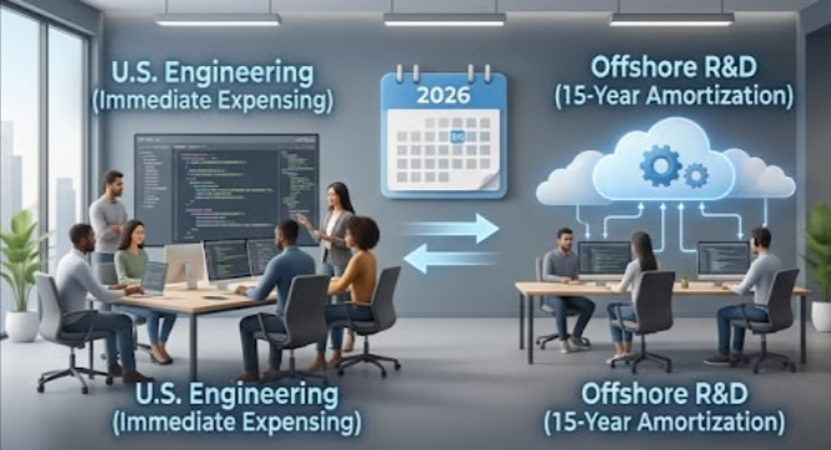
Under recent legislative adjustments—most notably provisions shaping the 2026 filing year—domestic Research & Experimental (R&E) expenditures have shifted back toward immediate expensing options (under Section 174A frameworks). Tech Tax Strategy.
Domestic R&D and Software Development
Domestic payroll and software architecture expenses now qualify for immediate expensing or accelerated amortization options.
Tax departments can evaluate accelerating unamortized balances carried over from prior tax years to optimize current net operating losses (NOLs) and improve cash flow.
Foreign and Offshore Engineering
Software development and research conducted overseas remain subject to a mandatory 15-year capitalization schedule.
Tax teams must carefully bifurcate foreign contractor payments from domestic engineering payroll to avoid audit exposure.
2. Tech Tax Strategy Maximizing Technology Tax Credits & Incentives
Tax credits remain a primary vehicle for reducing effective tax rates (ETR). However, claiming them requires robust, audit-ready substantiation that links financial accounting directly to technical execution.
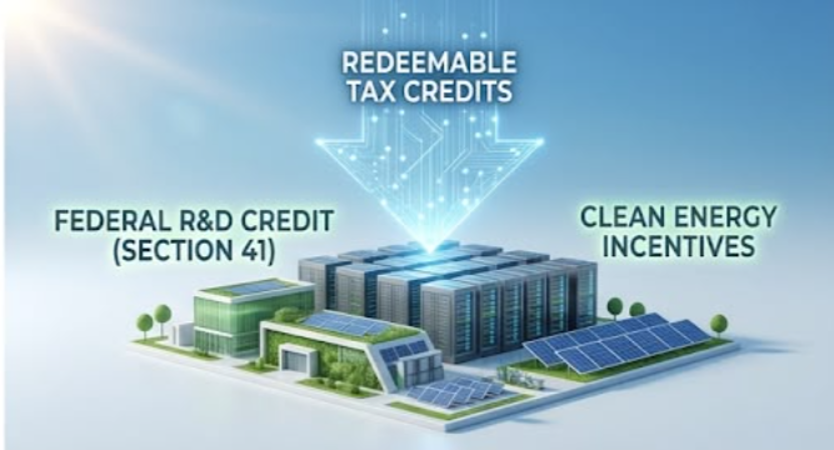
The Federal R&D Tax Credit (Section 41)
The Research and Development credit continues to be a cornerstone for software engineering, AI model training, database architecture redesign, and cloud infrastructure optimization.
The Four-Factor Test: Ensure software development projects meet IRS requirements: permitted purpose, elimination of technical uncertainty, process of experimentation, and technological in nature.
Section 280C Coordination: Finance teams must carefully model the interaction between Section 41 credits and Section 174A deductions. The restored reduction requirements necessitate assessing whether taking reduced credits or full deductions offers the strongest cash result. Tech Tax Strategy
Transferable Clean Energy & Infrastructure Credits
Following expanding transferable tax credit markets, tech companies operating enterprise data centers or investing in sustainable IT infrastructure can purchase tax credits at a discount. This strategy allows profitable tech firms to reduce dollar-for-dollar tax liabilities while supporting corporate sustainability initiatives.
3. Tech Tax Strategy Global Operations: Pillar Two, GILTI, and Cross-Border IP
Mid-market and large technology companies rarely operate within a single jurisdiction. Software delivery models make international expansion seamless, but they also trigger complex global tax obligations.
OECD Pillar Two Implementation
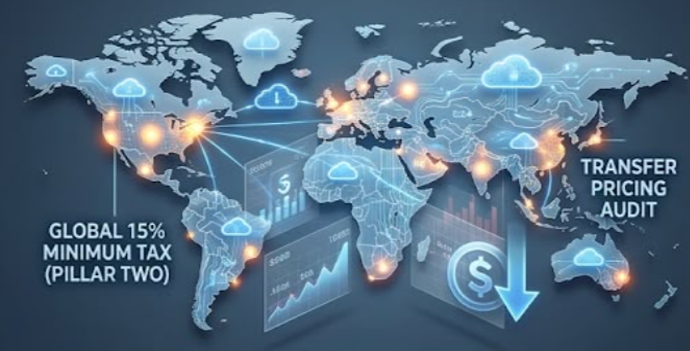
With OECD Pillar Two rules enforcing a global 15% minimum tax across major global jurisdictions, traditional offshore IP park strategies are far less effective. Tax departments must run continuous country-by-country modeling to ensure top-up taxes do not erode profit margins for entities earning over €750M in global revenue. Tech Tax Strategy
Transfer Pricing and Cloud Intercompany Service Agreements
As engineering teams distribute across North America, Europe, Asia, and Latin America, intercompany transactions must reflect strict arm’s-length standards. Tax authorities closely inspect royalty payments, software license allocations, and management service charges across cloud environments.
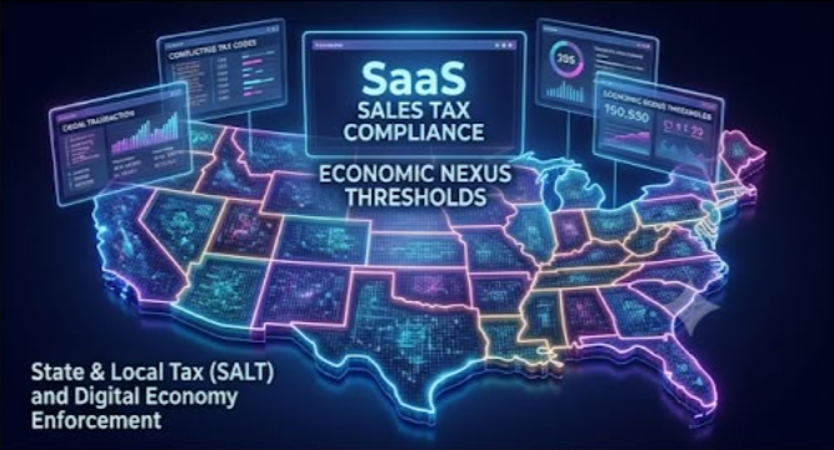
4. Tech Tax Strategy State & Local Tax (SALT) and Digital Economy Enforcement
State revenue departments are actively enforcing indirect tax policies. As software delivery moves entirely to SaaS, PaaS, and IaaS models, tracking nexus and taxability has become complex.
Key Focus Areas for State Tax Compliance:
Economic Nexus Beyond Sales Tax: States increasingly apply economic nexus rules to corporate income and franchise taxes, catching mid-sized software firms off guard as their remote customer base expands.
SaaS Taxability Sourcing: Sourcing revenue based on benefit-received rules versus cost-of-performance rules creates disparate tax burdens across state lines. Automated tax engine connectors integrated into billing engines are essential for managing real-time compliance.
Pass-Through Entity Tax (PTET): Tech founders and executive partners should leverage state-level PTET elections to optimize individual deductibility against federal income caps.
Strategic Action Plan for 2026
To transition the corporate tax function from a reactive cost center to a proactive driver of enterprise value, finance leaders should execute four key steps:
1. Conduct an Immediate R&D Cost Segmentation Analysis: Separate domestic software engineering payroll from international development resources to maximize immediate deduction elections.
2. Implement Transferable Credit Strategies: Evaluate purchasing high-grade energy credits to offset up to 10–15% of net corporate tax liabilities at a discount.
3. Audit State Indirect Tax Exposure: Perform a baseline multi-state nexus review for SaaS sales and remote workforce footprints to resolve exposure before pursuing funding or M&A.
4. Deploy Modern Tax Technology: Integrate automated tax engine connectors directly into ERP and subscription-billing software to track compliance real-time across jurisdictions.
Conclusion
Corporate tax planning in 2026 requires continuous alignment between financial strategy, product architecture, and legislative changes. By capitalizing on U.S. domestic research incentives, navigating global minimum tax obligations, and leveraging advanced tax automation tools, mid-range and large tech companies can protect cash reserves, improve profit margins, and fund their next phase of technological innovation.
References
[1] BDO USA (2026): Top Tax Planning Strategies for 2026: Section 1202, R&E Recovery, and Credit Arbitrage.
Top 10 Tax Planning Strategies for 2026 | BDO
[2] Thomson Reuters Institute (2025/2026): What Will Be the Impact of Section 174 in 2026? Strategic Planning for Software & R&D Expenses. What will be the impact of Section 174 in 2026? | Thomson Reuters Institute
[3] Thomson Reuters Corporate Tax Report (2026): 6 Insights from the 2026 Corporate Tax Technology Report: AI Integration and Data Readiness.Corporate Tax Technology Report 2026 | Thomson Reuters Institute | Thomson Reuters
[4] RSM US (2026): Top Trends for Tax Technology in 2026 and Beyond: Ecosystems, Data Readiness, and Governance. Top trends for tax technology in 2026 and beyond | RSM US
[5] Precedence Research (2026): Global Tax Tech Market Size, Growth, and Enterprise Adoption Trends (2025–2034). Tax Tech Market Companies, Size & Trends 2026-2035
[6] Internal Link: Add Post ‹ Eve Consultancy — WordPress
Report
AI Report
Plagiarism Report
Proofreading Report