Corporate Tax Strategy As the financial year draws to a close, Chief Financial Officers and finance leaders face a familiar, high-stakes moment: closing the books while making sure tax strategy aligns cleanly with broader corporate growth. In a business climate shaped by shifting economic conditions, changing tax rules, and active deal markets, waiting until the first quarter to evaluate your tax position simply leaves value on the table.
Year-end tax planning is far more than a standard compliance routine. When handled strategically, it serves as a reliable tool for preserving cash, protecting enterprise value, and setting up smooth corporate transactions. Whether your executive team is preparing for a future acquisition, integrating a recent business merger, or optimizing your overall capital structure, this checklist covers the essential levers to address before the close of the fiscal year. Corporate Tax Strategy plays a vital role in helping CFOs manage year-end financial responsibilities while preparing for mergers and acquisitions (M&A). By reviewing financial records, identifying tax-saving opportunities, assessing potential risks, and ensuring regulatory compliance, businesses can make smarter financial decisions. A well-planned approach to corporate taxation and M&A helps organizations improve financial efficiency, manage liabilities, and support long-term business growth.
1. Corporate Tax Strategy Optimize Capital Expenditure and Asset Strategy
Taking a close look at planned and existing capital assets before year-end offers quick cash-flow advantages that directly strengthen the bottom line.
Accelerate Qualifying Capex: Review upcoming equipment, technology, and facility spending. Pulling planned purchases into the current tax year allows your business to record eligible write-offs earlier.
Leverage First-Year Depreciation Rules: Check applicable statutory allowances for first-year and bonus depreciation. Evaluate whether cost segregation studies on recent real estate investments or facility upgrades can reclassify assets into shorter recovery periods.
Audit the Fixed Asset Register: Run a year-end review to locate obsolete, broken, or retired assets. Properly clearing unserviceable equipment from the books reduces local property tax burdens and lets you recognize allowable abandonment losses.
A successful Corporate Tax Strategy requires CFOs to carefully evaluate upcoming transactions, tax obligations, and overall business performance before the financial year closes. During mergers and acquisitions, companies must assess tax implications, review financial agreements, and identify potential compliance challenges. By working closely with tax professionals and financial teams, CFOs can improve transparency, minimize unexpected costs, and ensure that every strategic decision supports the company’s financial goals.
2. Corporate Tax Strategy Strategic M&A Tax Planning: Pre-Acquisition and Buy-Side Focus
If corporate acquisitions are on your growth agenda, tax planning needs to happen well before final purchase agreements are signed. Decisions made early in the M&A process directly influence valuation, deal terms, and post-closing profitability.
Evaluate Deal Structures Carefully: Work closely with deal counsel to weigh the advantages of asset purchases versus stock purchases. Asset deals often deliver a favorable step-up in tax basis for the buyer, while stock purchases may offer simpler execution and specific benefits for sellers.
Conduct Thorough Tax Due Diligence: Look beyond basic financial statements. Examine historical target filings, sales tax and indirect tax exposures, and cross-border transfer pricing setups to avoid inheriting unexpected tax obligations.
Preserve Valuable Tax Attributes: Review regulatory rules that limit how net operating losses (NOLs) and tax credits carry over after an ownership change, ensuring those assets retain their expected value post-acquisition.
3.Corporate Tax Strategy Post-Merger Integration and Corporate Restructuring
For companies that completed a business merger or transaction earlier in the year, the final quarter is the ideal window to capture planned operational synergies and organize corporate tax profiles.
Simplify Legal Entity Structures: Eliminate redundant legal entities created during past transactions. Cleaning up complex corporate structures lowers ongoing administrative expense and reduces multi-jurisdiction filing requirements. Corporate Tax Strategy.
Align Transfer Pricing Models: Make sure cross-border intercompany services, management fees, and intellectual property licensing arrangements across newly combined operations follow arm’s-length standards and match current operational reality.
Review Intercompany Debt and Equity: Re-examine intercompany loan agreements and corporate debt levels. Ensure interest expense deductions remain well within statutory limits across all operating subsidiaries.
4. Corporate Tax Strategy Maximize R&D Credits and Innovation Incentives
Tax credits directly reduce dollar-for-dollar tax liabilities, making them considerably more impactful than routine tax deductions. Corporate Tax Strategy .
Look Broadly at Eligible R&D Spending: Expand your internal review beyond traditional lab environments. Software development, internal process automation, custom engineering iterations, and technical updates often qualify for research credits.
Gather Solid Project Documentation: Collaborate with engineering, IT, and project managers now to gather contemporaneous records, developer logs, and payroll breakdowns before year-end.
Explore Green Energy Incentives: Review recent facility upgrades or fleet updates to identify applicable federal, state, or local tax incentives for energy efficiency and sustainable practices.
5. Corporate Tax Strategy Clean Up Balance Sheet Accounts and Compensation Structures
Strong balance sheet hygiene before year-end prevents unwelcome surprises during audit season and ensures proper timing for deductions. Corporate Tax Strategy.
Write Off Bad Debts and Adjust Reserves: Review aging accounts receivable. Identify and formally write off uncollectible accounts before the end of the year to capture legitimate bad-debt deductions.
Structure Executive Compensation and Bonuses: Finalize year-end performance bonuses and deferred compensation schedules. Make sure payments comply with tax timing rules to preserve corporate deductibility.
Reconcile Intercompany Balances: Settle intercompany accounts across subsidiaries to avoid accidental tax consequences triggered by currency swings or misclassified cash transfers.
Turning Strategy into Execution
Effective year-end tax planning demands steady collaboration among finance, legal, and operational leadership. By addressing capital investments, M&A structures, and internal efficiencies before the final calendar deadline, CFOs can transform tax management from a routine administrative obligation into a clear driver of enterprise value.
References
[1] Armanino LLP. Year-Round Tax Planning Checklist for Corporations. Armanino Knowledge Center. https://www.armanino.com/articles/year-round-tax-planning-checklist-for-corporations/
[2] PricewaterhouseCoopers (PwC). Mergers and Acquisitions (M&A) Tax Services: Structuring, Due Diligence, and Value Creation. PwC Global Tax Services. https://www.pwc.com/gx/en/services/tax/mergers-and-acquisitions.html
[3] EASMEA Corporate Advisory. The CFO’s Checklist for Year-End Financial Closing and Tax Compliance. EASMEA Insights. https://www.easmea.com/the-cfos-checklist-for-year-end-financial-closing/
[4] Internal Link: Add Post ‹ Eve Consultancy — WordPress
Report
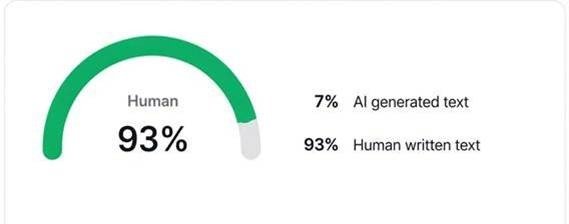
AI Report
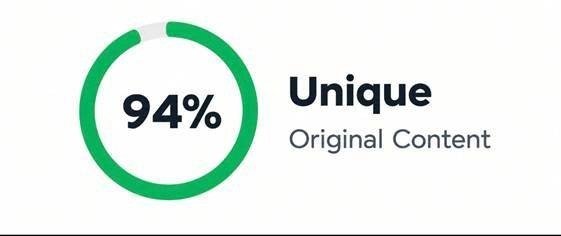
Plagiarism Report
Proofreading Report