1. 7 Important Changes Under the AS 22 Pillar Two Amendment
The AS 22 Pillar Two amendment introduces important changes to deferred tax accounting and disclosure requirements for companies affected by global minimum tax rules.
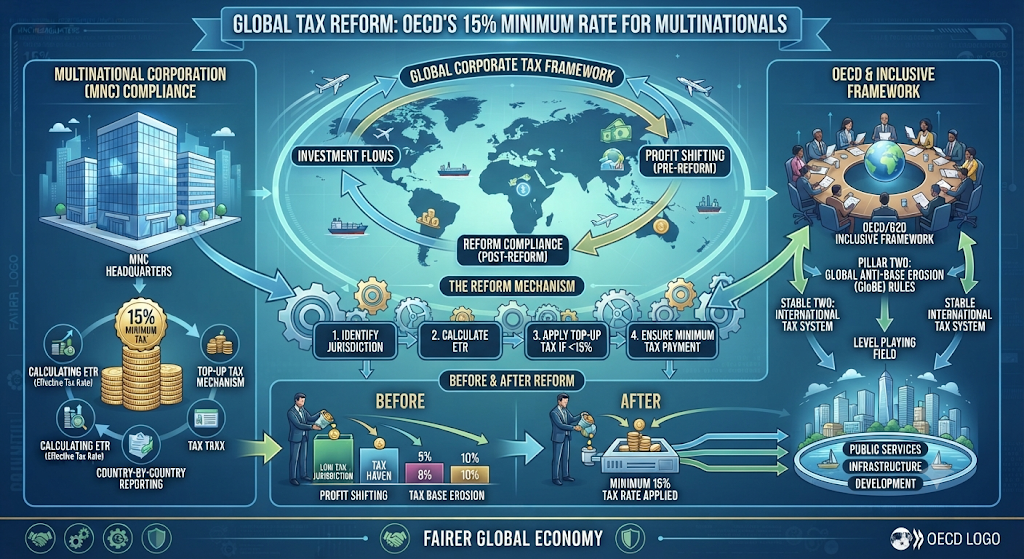
Pillar Two Model Rules by the OECD have transformed international taxation and the way it works. The main point of the new rules is that major international organizations or MNEs operating in a particular jurisdiction are to bear a minimum effective tax of 15%. Due to difficulties that arise from such rules in the area of accounting, changes in Accounting Standard (AS) 22, Accounting for Taxes on Income, have been made. These changes were introduced through Companies (Accounting Standards) Amendment Rules, 2026.
Companies should also understand the Pillar Two deferred tax rules in India to assess global minimum tax exposure and prepare accurate financial disclosures.
2. What Pillar Two
Pillar Two is part of the global tax reform by the OECD which is aimed at avoiding tax avoidance and profit shifting by multinational big businesses. MNEs that fall under this category are required to pay a minimum tax of 15%. If the effective tax rate of these companies is lower than the provided amount, top-up tax or another tax may be imposed.
3. Temporary Exception for Deferred Taxes
The AS 22 amendment introduces an important feature as it allows the temporary exception from recognizing and disclosing deferred tax assets (DTA) and deferred tax liabilities (DTL) that result from the Pillar Two taxation.
This relief takes into account the intricacies in the calculation of deferred taxes according to the new global tax system. However, the exception only applies to the taxes connected with Pillar Two. Other than that, companies still have to comply with the usual AS 22 rules pertaining to all their deferred tax items relating to income tax.
4. New Disclosure Requirements
Even though the amendment eases deferred tax accounting, it also imposes new rules with regard to disclosures given under paragraphs 32A–32D.
The most significant disclosures are:
Application of the exception: Companies will need to disclose the application of the Pillar Two deferred tax exception.
Current tax disclosure: Companies should disclose their current tax expense or income arising from Pillar Two taxes separately.
Potential tax exposure: Companies will have to disclose qualitative and quantitative information regarding their exposure to Pillar Two taxes.
5. Applicability and Effective Date
The amendments came into force with the publication in the Official Gazette in March 2026. The deferred tax exception applies immediately and retroactively whereas additional disclosure requirements are applicable to the annual reporting periods which start on or after April 1, 2025. Specific small and medium enterprises will be exempt from disclosing some exposure-related information.
6. Impact on Accountants
The amendment obliges accountants to pay attention to international tax changes and their influence on financial reports. They should identify relevant tax exposures, cooperate with tax teams, and ensure accurate reporting. Auditors must also check the correct utilization of the exception and compliance with the newly introduced disclosures.
7. Conclusion
The amendments to AS 22 have become a landmark event in bringing Indian accounting closer to the global development of tax regulations. The deferred tax exception makes accounting easier, and on the other hand, additional disclosures promote transparency and accuracy of information. Accountants should master these changes in order to be compliant with them.
References
[1] Ministry of Corporate Affairs, Government of India, “The Companies (Accounting Standards) Amendment Rules, 2026,” G.S.R. 169(E), Mar. 10, 2026.
[2] Organisation for Economic Co-operation and Development, Tax Challenges Arising from the Digitalisation of the Economy: Global Anti-Base Erosion Model Rules (Pillar Two). Paris, France: OECD Publishing, 2021.
[3] IFRS Foundation, “IAS 12—Income Taxes: International Tax Reform—Pillar Two Model Rules.” [Online]. Available: https://www.ifrs.org/issued-standards/list-of-standards/ias-12-income-taxes/