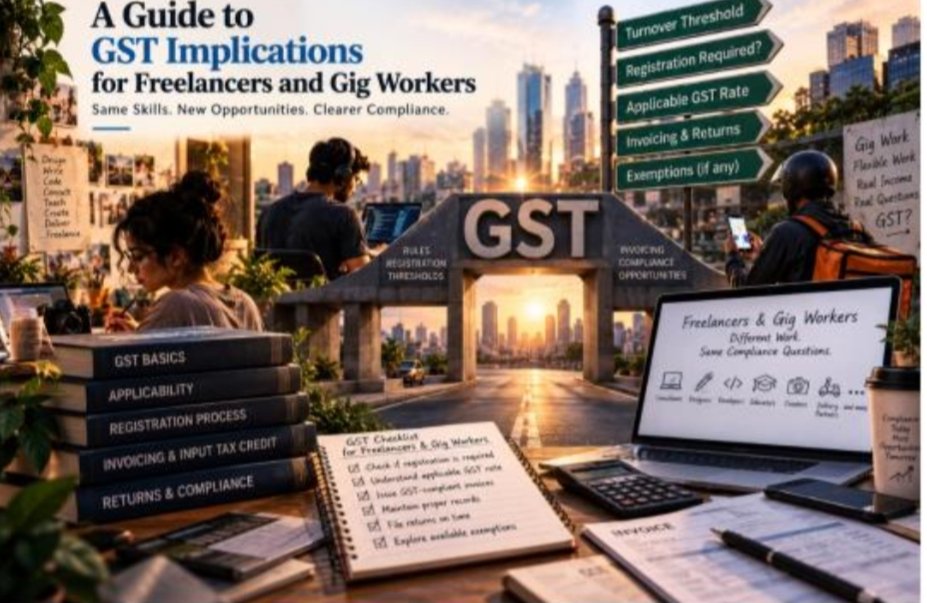
A Guide to GST Implications for Freelancers and Gig Workers
Published: Oct 10, 2026
Key Highlights
- GST for freelancers depends on aggregate turnover, the nature of services supplied, and applicable GST registration rules.
- The general registration threshold for service providers is ₹20 lakh in aggregate turnover per financial year, with a lower threshold applying in certain states, subject to applicable provisions.
- Freelancers should assess their total aggregate turnover rather than income from an individual client.
- Suppliers dealing exclusively in wholly exempt services may qualify for relief from GST registration, subject to applicable conditions.
- GST for freelancers making inter-State supplies of services may be subject to specific registration exemptions, depending on their turnover and eligibility.
Trend
Freelancing and gig work are gaining momentum as acceptable means of earning income, but GST implications for them can prove complicated as one goes from working with one client or platform to working with several. The question of whether a person is a freelancer or a gig worker is irrelevant compared to whether one is supplying goods or services independently and whether turnover or nature of supplies triggers GST registration liability. These implications can become a headache if not evaluated in advance.
GST for Freelancers
For most independent service providers, GST registration liability emerges when their total turnover exceeds the specified threshold. The general threshold for suppliers of services is ₹20 lakh in a financial year, with a ₹10 lakh threshold for certain special-category states. Thresholds also apply to aggregate turnover and not the turnover from any one client. Other categories may apply depending on the nature and location of supplies, which means that a freelancer must take these factors into account.
Someone who supplies services that are entirely exempt from GST is unlikely to be required to register for GST simply based on their turnover. The same applies to other special cases for particular suppliers of services that fall below the threshold. In other words, a Gig freelancer, like any other taxpayer, needs to assess the category of supplies they deal in before determining if the registration threshold rules apply or if they can rely on an exemption.
Gig Workers
workers are also considered independent contractors, but they represent a disparate group of individuals who provide services through an online platform. In this case, too, the location and nature of supplies apply for determining GST liability. Someone who provides services through an online platform should not assume that being a “gig worker” triggers GST registration on the mere fact that they are a contractor. In particular, they must consider whether they are supplying goods and services independently.
Moreover, the government has set a special exemption for service suppliers with a turnover up to ₹20 lakhs who make inter-State supplies of services from the requirement of registration. This rule can apply to many freelancers who often work with clients outside their state and get away without a GST registration.
GST Registration Process
If someone finds that they are required to register for GST, they will need to apply online via the GST portal. They can begin the process by filling up the PAN, mobile number, and email address, performing an OTP-based verification and generating a Temporary Reference Number (TRN). They will have to fill up their business details and service details and perform Aadhaar-based authentication or any other process mandated by the portal to submit the application for GST registration. After approval, they will receive the GST Identification Number (GSTIN) and the certificate of registration.
Responsibilities After Registration
Being a GST taxpayer comes with responsibilities in addition to the right to deduct tax for supplies made. Depending on their nature, location, and other factors, a freelancer or a gig worker may need to invoice their clients as GST-registered suppliers and add GST to the price of their services. They can get a detailed analysis of their GST obligations based on their category and their liabilities under the GST law, including what returns they will be required to file and what invoices or other documents they need to keep for record-keeping purposes. They, therefore, need to consider GST implications for their business in advance of filing GST tax returns and not leave it as an added expense.
Conclusion
For freelancers and gig workers, GST liability depends on more than the label attached to their work. Turnover, the nature of services, location of customers, and specific GST exemptions or registration provisions all matter. Checking these factors before crossing the relevant threshold can help independent workers understand when GST for freelancers becomes applicable and avoid unnecessary compliance problems.
Key Regulatory Takeaways-
GST for freelancers depends on aggregate turnover, the nature of services supplied, and applicable GST registration rules.
The general registration threshold for service providers is ₹20 lakh in aggregate turnover per financial year, with a lower threshold applying in certain states, subject to applicable provisions.
Freelancers should assess their total aggregate turnover rather than income from an individual client.
Suppliers dealing exclusively in wholly exempt services may qualify for relief from GST registration, subject to applicable conditions.
GST for freelancers making inter-State supplies of services may be subject to specific registration exemptions, depending on their turnover and eligibility.
FAQs
What is the GST registration threshold for freelancers?
The general threshold for service providers is ₹20 lakh in aggregate turnover during a financial year. A lower threshold of ₹10 lakh applies in certain special-category states, subject to applicable rules and exceptions.
Is GST registration mandatory for every freelancer?
No. GST for freelancers depends on applicable registration thresholds, the nature of supplies, and specific legal provisions. Some freelancers may qualify for exemptions or may not be required to register.
Statutory Citations & References
[1] Central Board of Indirect Taxes and Customs, Government of India, “Registration and Threshold,” 2019. [Online]. Available: CBIC GST
[2] Central Board of Indirect Taxes and Customs, Government of India, “Goods and Services Tax: Registration,” [Online]. Available: CBIC GST Registration Rules
[3] Goods and Services Tax Network, “Apply for Registration: Normal Taxpayer,” [Online]. Available: GST Portal
Maximize Your Business Potential
Looking for a partner to advise on GST, ITR, Business Registration, or Financial Strategy? Our experts ensure your compliance is seamless and your solutions are optimized.
Book a Strategy ConsultationEve Finance: Your Daily Financial Eve-olution!
Finance made simple, fast, and fun! 🏦💡 Sign up for your daily dose of financial insights delivered in plain English. In just 5 minutes, you’ll be smarter and better!